Ownership with intention starts before the search, before the pre-approval, before the first showing.September always feels different to me.It is the end of the third quarter. It is the last month

Dated: June 19 2026
Views: 231
There is a version of the housing market that a lot of people are still carrying around in their heads.
A version with 3% mortgage rates. A version where homes seemed to appreciate almost by the week. A version where people were bidding over asking, waiving contingencies, refreshing listings like it was a competitive sport, and trying to get into anything that looked remotely livable before someone else did.
A version where more space suddenly felt urgent. Where working from home made distance feel less expensive. Where people started rethinking bedrooms, basements, backyards, school districts, office corners, and what “home” needed to do in a world that had become frighteningly unpredictable.
That market was real.
But it was not normal.
And that distinction matters.
Because a lot of today’s frustration is not just about rates, prices, inventory, or monthly payments. It is about comparison.
People are comparing today’s market to a market that was shaped by extraordinary conditions. They are measuring present reality against a moment that felt like access, urgency, fear, opportunity, and chaos all at the same time.
And when memory becomes the benchmark, reality starts to feel like failure.
That is where people get stuck.
Not because they are irrational.
Because they are human.
We do not compare today’s market to history as much as we compare it to the version of the market that made us feel like something was still within reach.
That is the problem.
Not just the rate.
Not just the price.
Not just the house.
The reference point.
The Market We Remember
For many people, the market they are still responding to is not the one they are actually standing in.
It is the one they remember. Or the one they almost entered. Or the one they watched from the sidelines. Or the one they now believe they missed.
For some, that memory is 2020. For others, it is 2021. For others, it is early 2022, when they could still see remnants of that market before the door started closing in a different way.
The details vary.
But the emotional imprint is similar.
Rates were low. Demand was high. Prices were rising. People were moving. Homes were becoming emotional lifeboats, not just financial assets.
That matters.
Because people were not simply making housing decisions during that period. They were making housing decisions during a global disruption.
The pandemic did not just change where people lived.
It changed what people expected from home.
Home became office, classroom, refuge, gym, care center, storage unit, creative space, and emotional shelter. Sometimes, it became the only place where people felt they had any control.
So when people look back at that period, they are not only remembering a mortgage rate.
They are remembering a feeling.
The feeling that if they moved quickly enough, they could secure space. The feeling that if they got in, the market would lift them. The feeling that homeownership was still possible if they just caught the right wave.
But waves are not floors.
And an anomaly is not a baseline.
That period was not a normal real estate cycle gently doing what real estate cycles do. It was a collision.
A global pandemic. Government intervention. Monetary policy. Supply chain disruption. Remote work. Lifestyle migration. Fear. Stimulus. Low borrowing costs. Inventory pressure. A massive appetite for space during a time when everyone was forced to confront how fragile ordinary life could be.
Those forces did not just affect the market.
They rewired expectations.
And expectations are powerful. They can help people plan. They can also make people wait for a world that has already moved.
The 3% Mortgage Problem
Let me be clear: low mortgage rates were not a problem in themselves.
They helped millions of buyers reduce borrowing costs, increase purchasing power, and secure housing during a period of significant uncertainty. For households that were able to buy or refinance at those rates, the financial benefits were substantial.
The issue is not that people should not have taken them.
If someone bought well, bought wisely, and locked in a historically low rate that supported their life and numbers, good.
That was not a mistake.
The problem is what happened afterward.
Many consumers quietly began treating 3% as normal.
Not officially. Not always consciously.
But emotionally.
Three percent became the ghost in the room. It became the number people kept measuring everything against.
A 6% rate did not feel like 6%.
It felt like “not 3.”
A 7% rate did not feel like 7%.
It felt like punishment for being late.
That is how anchoring works. Once your mind attaches to a reference point, everything else gets interpreted through it.
And in housing, that can become expensive.
Because if your strategy is built around waiting for an extraordinary condition to repeat, you may not be planning.
You may be grieving.
That does not mean rates do not matter.
They absolutely matter.
A rate changes payment. A payment changes buying power. Buying power changes options. Options change strategy.
But there is a difference between respecting the math and worshiping the memory.
Three percent was a gift for the people who caught it.
It was not a promise to everyone who came after.
And that is where the market conversation gets uncomfortable.
Because nobody wants to hear that the number they are waiting for may not be the number they should build a plan around.
But time does not become leverage just because you wait.
Time becomes leverage when you use it to reposition.
Waiting for a past rate to return is not the same as preparing for the market that exists.
One is nostalgia.
The other is strategy.
Prices Did Not Fall Back Into the Old Story
This is the other side of the frustration.
People are not only anchored to old rates. They are anchored to old prices.
They remember the house that used to be $275,000. The neighborhood that used to feel reachable. The starter home that used to be a little worn but possible. The townhouse that once sat in a range that made sense for a first-time buyer with decent income, modest savings, and some patience.
Now that same buyer opens the search and sees something completely different.
Maybe the homes are still there, but the price points are not. Or the homes in the old range need more repairs than the buyer can afford after closing. Or the location has shifted farther out. Or the payment does not work once the current rate, taxes, insurance, HOA fees, and debt-to-income realities enter the conversation.
That is not imaginary.
People are not making up the squeeze.
Some prices have softened in some places. Some listings sit longer. Some sellers are making concessions. But a modest correction is not the same thing as a return to a prior era.
That is where many people misread the market.
They hear “prices are coming down” and imagine a reset.
But often what comes down is not enough to restore the old entry point. A home that rose dramatically and then gives back a little has not necessarily become affordable again.
It has simply stopped running as fast.
That distinction matters.
Because buyers can lose a lot of time waiting for “prices to come down” without ever defining what “down” actually means.
Down to what?
Down to 2019?
Down to the payment they had in their head?
Down to the number their cousin paid before the pandemic?
Down to a price that works with today’s rate, today’s income, today’s debt, today’s taxes, and today’s cash-to-close?
Those are very different questions.
And real estate will punish vague waiting.
Not because the market is mean.
Because the market is specific.
The First Rung Moved
This is where the conversation becomes more than math.
For a lot of buyers, especially first-time buyers, younger buyers, moderate-income buyers, and first-generation buyers, the issue is not simply that homes cost more.
It is that the entry point changed.
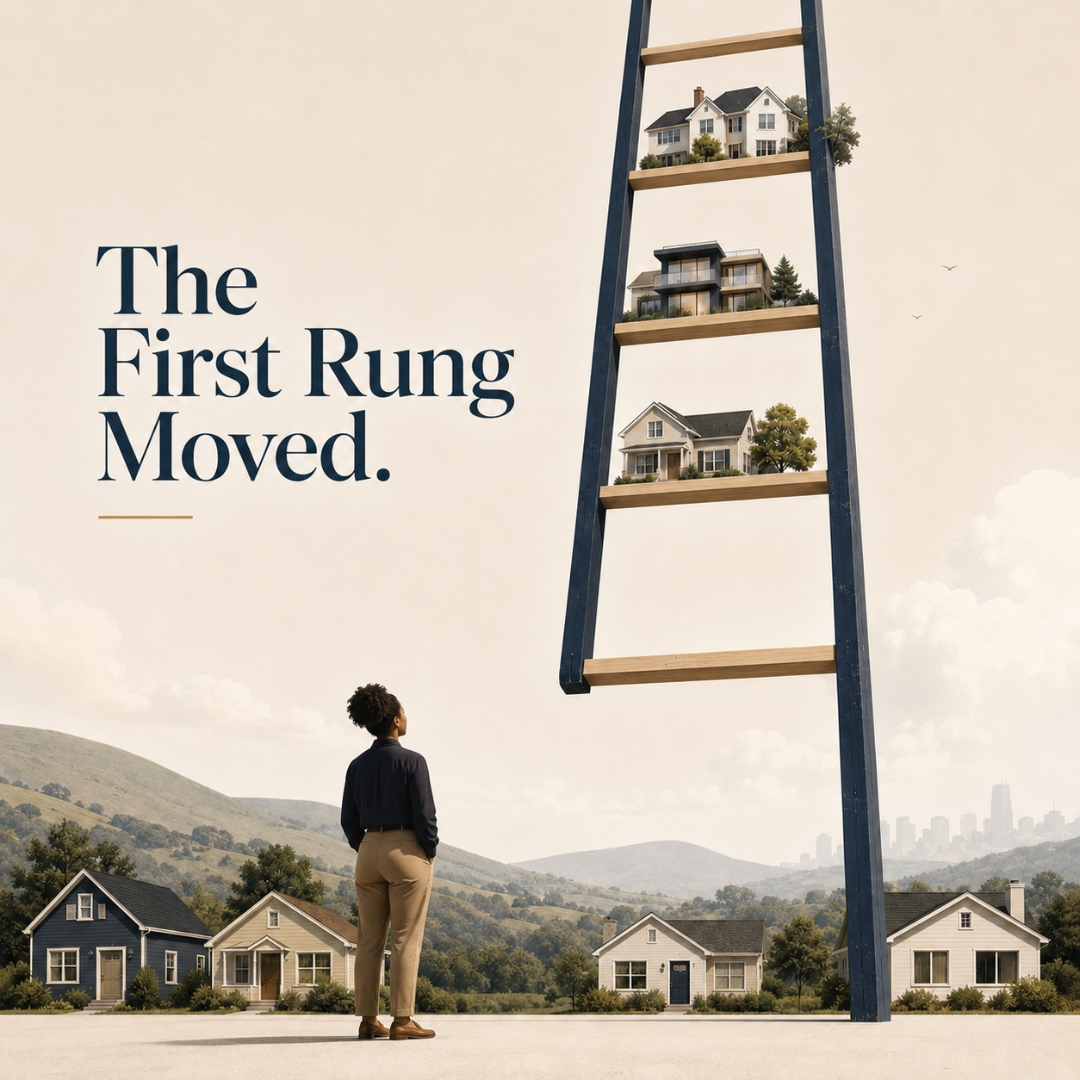
The ladder did not disappear.
The first rung moved.
And when the first rung moves, the whole climb changes.
People talk about starter homes as if they are just smaller houses. But historically, starter homes have served a much larger function.
They were the first step into equity. The first place to stabilize housing costs. The first asset some families ever owned. The first opportunity to stop being only a tenant in someone else’s investment plan.
The first rung was never just about square footage.
It was about access.
So when that rung moves higher, the impact is not evenly distributed.
A buyer with family help may still climb. A buyer with existing household wealth may still adjust. A buyer who can sell something else, borrow from relatives, or receive a gift may still find a way.
But a first-generation buyer does not always have another rung underneath them.
There may be no parent with equity to borrow against. No family property to sell. No quiet transfer of money that shows up as “help with closing.” No inherited stability disguised as personal discipline.
That matters.
And pretending it does not matter is dishonest.
This is also where politics and policy enter the room whether people want to name them or not.
Housing access is shaped by zoning decisions, development patterns, lending standards, wage growth, local tax structures, construction costs, investor activity, infrastructure, school boundaries, public transportation, and the long afterlife of who was allowed to buy where, when, and under what terms.
So no, the entry-level problem is not just about personal discipline.
But it is also not solved by pretending the old price points are still widely available.
Both things can be true.
The structure got harder.
And buyers still need a strategy for the structure they are actually in.
That is the tension.
That is the work.
When Work Changed, Housing Changed
The pandemic did not just change housing demand.
It changed the meaning of distance.
For a while, the commute became theoretical for many workers. A longer drive did not feel as expensive if the office was only a laptop away. A larger home farther out felt more reasonable if the trade-off was space, quiet, land, parking, and a room with a door that could become an office.
People did not simply buy bedrooms.
They bought a theory of life.
They bought the idea that work had changed. That flexibility had become permanent. That geography had loosened its grip.
And for some people, that was true.
For others, it was true until it was not.
Return-to-office policies changed the calculation. Employer decisions changed the value of distance again. A house that made sense when work happened at the kitchen table may feel different when the commute returns three, four, or five days a week.
A location that felt like freedom can start to feel like friction.
A home that solved one version of life can become complicated inside another.
That does not mean those buyers made bad decisions.
It means they made decisions inside a particular time.
And time changed the assumptions underneath them.
That is why housing decisions cannot be separated from work policy.
Employer policy is housing policy in disguise.
When companies decide where people must be physically located, they are not only managing office culture. They are reshaping commute burdens, childcare logistics, household time, location value, and the practical meaning of affordability.
Because affordability is not only the mortgage payment.
It is the payment plus the commute. The payment plus the gas. The payment plus the time. The payment plus the life that purchase requires you to live.
That is why this market feels so layered.
People are not just asking, “Can I afford the house?”
They are asking, “Can I afford the life attached to the house?”
That is a deeper question.
And it deserves a deeper answer than “buy now” or “wait.”
The Collision We Don’t Always Like to Name
Sometimes people want one villain in the housing story.
Rates. The Fed. Politicians. Investors. Greedy sellers. Builders. Remote work. Low inventory. Inflation.
And depending on the market, several of those may deserve a seat at the table.
But no single explanation is enough.
Housing over the last several years was shaped by a collision of forces: public policy, monetary policy, employer policy, consumer behavior, pandemic reality, supply constraints, political choices, institutional incentives, and personal fear.
That is why the conversation gets messy.
Because housing is where policy becomes personal.
A rate decision becomes a monthly payment. A zoning decision becomes a shortage. A corporate office policy becomes a commute. A wage gap becomes a denied pre-approval. A student loan payment becomes a debt-to-income problem. A family’s lack of inherited wealth becomes “not enough cash to close.” A market headline becomes somebody’s kitchen table conversation at 11:30 at night.
That is why I do not like real estate commentary that pretends politics do not touch real life.
They do.
Not always in the loud campaign-slogan way people argue about online.
But in the quieter, more structural way.
Who gets access. Who gets delayed. Who gets priced out. Who gets protected. Who gets told to wait. Who gets told they should have moved sooner.
The market is not floating above people’s lives.
It is sitting directly inside them.
And when we pretend otherwise, we make the conversation smaller than it needs to be.
That does not mean every article has to become partisan.
It means responsible housing commentary has to be honest about structure.
Memory simplifies what reality complicates.
Memory says: rates used to be lower, prices used to make more sense, people used to have more flexibility, and the market used to be better.
Reality says: the market was different because the conditions were different.
And conditions matter.
Time Can Clarify — Or It Can Distort
This is the part I keep coming back to.
Time is not automatically leverage.
Sometimes time helps. Sometimes it gives a buyer space to improve credit, reduce debt, save cash, understand the market, clarify location, or make a better decision.
That is time used well.
But time can also distort.
The longer people hold onto a market memory, the more that memory can harden into a demand.
“I’m waiting for rates to drop.”
“I’m waiting for prices to come down.”
“I’m waiting for things to go back to normal.”
But what if normal is the wrong word?
What if what people are really waiting for is not normal?
What if they are waiting for a rare alignment of conditions that made access feel closer than it had any right to feel under the circumstances?
That is not a moral judgment.
It is a strategic question.
Because waiting can be wise.
But waiting without recalibration is dangerous.
At some point, the question cannot only be:
“Will the market change?”
The question also has to become:
“Have I changed my strategy to match the market I’m actually in?”
That is where leverage begins.
Not in pretending the present is easy. Not in romanticizing the past. Not in panicking because the current market feels harder.
Leverage begins when the buyer stops negotiating with memory and starts reading structure.
The current rate. The current inventory. The current entry point. The current payment. The current work reality. The current underwriting standard. The current household budget. The current life.
That is not as emotionally satisfying as waiting for the old market to reappear.
But it is more useful.
And useful matters.
The Real Question
The question is not simply:
“Will rates come back down?”
Or:
“Will prices ever go back to normal?”
Or:
“Is now a good time to buy?”
Those questions are not wrong.
They are just incomplete.
The better question is this:
What if the version of normal we keep referencing was never normal at all?
Because if the reference point is wrong, the strategy will be wrong too.
A buyer can spend years waiting for a rate that does not return. A seller can overprice because they remember the frenzy. A renter can keep delaying because the old entry point still feels like the “real” price. A household can keep making decisions from a market memory instead of a market analysis.
And the danger is not simply missing one house.
The danger is losing time.
Time that could have been used to prepare. To reposition. To adjust expectations without lowering standards. To understand tradeoffs. To build reserves. To strengthen the file. To clarify whether the goal is still the same or whether the path to the goal has changed.
Because that is the nuance.
Adjusting to reality does not mean giving up.
It means refusing to let an old market memory make your decisions for you.
The market we remember is a story.
The market we occupy is a structure.
And leverage lives in the structure, not the story.
That does not mean people are wrong to feel frustrated.
A lot of the frustration is justified.
The first rung did move. The payment pressure is real. The price points are tighter. The old search ranges do not always exist in meaningful numbers anymore. And for many buyers, especially those without inherited wealth or family backup, the climb is objectively harder.
But clarity requires us to tell the truth in both directions.
Yes, the structure changed.
And yes, the strategy has to change with it.
Real estate decisions get clearer when we stop asking time to move backward.
And start asking what readiness looks like here.
Now.
In this market.
Under these conditions.
Because memory can explain the tension.
But it cannot make the decision.
Before Memory Becomes the Strategy
If your housing plan still depends on rates, prices, or conditions recreating 2020 or 2021, it may be time to recalibrate.
That is part of what BBP90 is built to do.
Not pressure. Not hype. Not aspiration without structure.
Just a clearer way to understand what today’s market is actually asking of buyers — and what readiness really looks like inside it.
https://click.lh-re.co/your-BBP90
Lisa Hoover is a real estate broker associate with Douglas Realty who supports people across the real estate ecosystem in making thoughtful, well-timed decisions—whether they are preparing, repo....
Ownership with intention starts before the search, before the pre-approval, before the first showing.September always feels different to me.It is the end of the third quarter. It is the last month
A first home does not have to be the final home. It does not have to answer every prayer, solve every family goal, and carry the full weight of legacy on day one. It should matter. It should serve
Expectation Before AspirationSaturday nights in our house ran on cardboard money and plastic deeds. We played Monopoly until someone mortgaged Boardwalk, then reset the board and switched to The
There is a version of the housing market that a lot of people are still carrying around in their heads.A version with 3% mortgage rates. A version where homes seemed to appreciate almost by the.
 Copyright© 2026 REIN Inc. Information Deemed Reliable But Not Guaranteed. The listings data displayed on this medium comes in part from the Real Estate Information Network Inc.(REIN) and has been authorized by participating listing Broker Members of REIN for display. REIN's listings are based upon Data submitted by its Broker Members, and REIN therefore makes no representation or warranty regarding the accuracy of the Data. All users of REIN's listings database should confirm the accuracy of
the listing information directly with the listing agent. Copyright ©2026 REIN. REIN's listings Data and information is protected under federal copyright laws.Federal law prohibits, among other acts, the unauthorized copying or alteration of, or preparation of derivative works from, all or any part of copyrighted materials, including certain compilations of Data and information. COPYRIGHT VIOLATORS MAY BE SUBJECT TO SEVERE FINES AND PENALTIES
UNDER FEDERAL LAW.
REIN updates its listings on a daily basis. Data last updated: September 24, 2026 12:16 PM UTC
Show More...
 All or a portion of the multiple listing information is provided by the Central Virginia Regional Multiple Listing Service, LLC, from a copyrighted compilation of listings. All CVR MLS information provided is deemed reliable but is not guaranteed accurate. The compilation of listings and each individual listing are ©2026 Central Virginia Regional Multiple Listing Service, LLC. All rights reserved.
All MLS listings are © 2026 Central Virginia Regional Multiple Listing Service, LLC. All
rights reserved. No one may copy and/or repost these MLS listings, or any portion thereof, without the written permission of an authorized officer of the Central Virginia Regional Multiple Listing Service, LLC.
All listings with the CVRMLS logo are provided courtesy of the IDX program.
Last Updated: September 24, 2026 12:32 PM UTC
Show More...
 Copyright © MFRMLS.com All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Information on this site was last updated Last updated on September 24, 2026 12:41 PM UTC The listing information on this page last changed on Last updated on September 24, 2026 12:41 PM UTCd. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of MFR MLS.
All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing.
Updated on September 24, 2026 12:41 PM UTC
33. Required DMCA Notice
The Digital Millennium Copyright Act of 1998, 17 U.S.C. §512, the DMCA, provides recourse for copyright owners who believe that material appearing on the Internet infringes their rights under U.S. copyright law. If you believe in good faith that any content or material made available in connection with our website or services infringes your copyright, you (or your agent) may send us a notice requesting that the content or material be removed, or access to it blocked. Notices must be sent in writing by email to DMCAnotice@MLSGrid.com. The DMCA requires that your notice of alleged copyright infringement include the following information: (1) description of the copyrighted work that is the subject of claimed infringement; (2) description of the alleged infringing content and information sufficient to permit us to locate the content; (3) contact information for you, including your address, telephone number and email address; (4) a statement by you that you have a good faith belief that the content in the manner complained of is not authorized by the copyright owner, or its agent, or by the operation of any law; (5) a statement by you, signed under penalty of perjury, that the information in the notification is accurate and that you have the authority to enforce the copyrights that are claimed to be infringed; and (6) a physical or electronic signature of the copyright owner or a person authorized to act on the copyright owners behalf. Failure to include all of the above information may result in the delay of the processing of your complaint.
 © BRIGHT, All Rights Reserved
Information Deemed Reliable But Not Guaranteed
The data relating to real estate for sale on this website appears in part through the BRIGHT Internet Data Exchange program, a voluntary cooperative exchange of
property listing data between licensed real estate brokerage firms in which
participates, and is provided by BRIGHT through a licensing agreement.
The information provided by this website is for the personal,
non-commercial use of consumers and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing.
Data last updated: September 24, 2026 11:22 AM UTC
Some properties which appear for sale on this website may no longer be available
because they are under contract, have Closed or are no longer being offered for sale.
Some real estate firms do not participate in IDX and their listings do not appear on this website. Some properties listed with participating firms do not appear on this website at the request of the seller.
Show More...
 All or a portion of the multiple listing information is provided by the Williamsburg Multiple Listing Service, LLC, from a copyrighted compilation of listings. All WMLS information provided is deemed reliable but is not guaranteed accurate. The compilation of listings and each individual listing are ©2026 Central Virginia Regional Multiple Listing Service, LLC. All rights reserved.
All MLS listings are © 2026 Williamsburg Multiple Listing Service, LLC. All rights reserved. No one may copy and/or repost these MLS listings, or any portion thereof, without the written permission of an authorized officer of the Williamsburg Multiple Listing Service, LLC.
All listings with the WMLS logo are provided courtesy of the IDX program.
Last Updated: September 24, 2026 12:39 PM UTC
